Publish Date: 13-10-2025
Renter's insurance
Last Updated: 25-10-2026
Does Renters Insurance Cover Fire Damage?
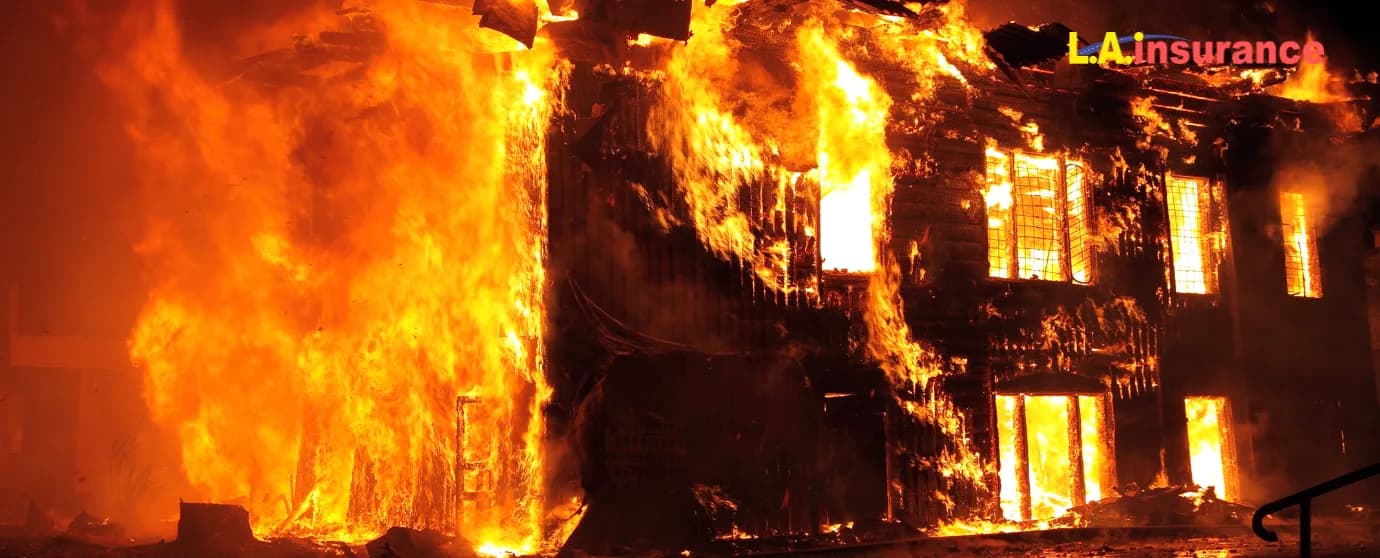
No matter how careful you are, accidents can happen, and a fire can destroy your personal belongings in a rental unit. That's why it's important to understand how renters insurance can help protect your belongings and finances after a fire.
If you're wondering whether renters insurance covers fire damage, the answer is generally yes. A standard policy typically covers personal belongings damaged by a covered fire. It may also cover additional living expenses if your rental becomes uninhabitable and personal liability if you're legally responsible for covered injuries or property damage.
However, coverage depends on your policy's terms, exclusions, and limits. In this article, we'll explain what renters insurance covers after a fire, what it excludes, and how you can protect yourself from unexpected expenses.
Quick Answer: Does Renters Insurance Cover Fire?
- Yes, most renters insurance policies cover fire damage and smoke damage to your personal belongings.
- Building repairs are generally your landlord’s responsibility, although your personal liability coverage may apply if you’re legally responsible for covered fire damage to the building.
- Coverage often includes loss of use for temporary housing and additional living expenses if your rental is unlivable.
- Common limits apply to high-value items (e.g., jewelry, electronics) unless you add extra coverage.
- Fires are covered if accidental; intentional fires or pre-policy events are excluded.
- To file a claim, notify your insurer immediately, document damaged or destroyed items, and keep receipts.
Does Renters Insurance Protect My Personal Property from Fire?
Yes, it does. A standard renters insurance policy will almost always cover fire damage to your personal property. Whether it’s a kitchen blaze, an electrical fire, or even a wildfire that sweeps through your neighborhood, you’re covered as long as you have the right kind of renters insurance policy (AKA HO-4 policy or tenant insurance).
If flames or smoke destroy your personal belongings, your insurance company will likely reimburse you. That includes your everyday items like clothing, furniture, or your favorite guitar.
However, your insurer may not pay the full cost of replacing damaged items with new ones. Your payout depends on your personal property coverage limit, deductible, and whether your policy pays actual cash value or replacement cost.
So, let’s say, your policy has $25,000 personal property coverage and a $500 deductible. If the fire ruins your $5,000 sofa and $2,000 laptop, you’d pay $500 first, and your insurer would pay the remaining $6,500, assuming the stated values reflect the applicable claim valuation and no other limits apply.
Types of Fire Accidents Covered by Renters Insurance Policy
You can’t judge all fire incidents equally. For example, accidental fire incidents are not your fault. But if you do it intentionally or out of anger, your insurance company will deny your claim.
Generally, the following types of fire accidents are covered by renters insurance:
- Kitchen fires, such as a fire caused by unattended cooking
- Electrical fires caused by faulty wiring or appliances
- Heating fires from space heaters or radiators
- Candle or smoking accidents
- Wildfires or lightning-sparked fires
- Chimney fires or other flue issues
- Fires that start in a neighboring unit or another person's home and damage your belongings
Your belongings may also be protected outside your home. Say your backpack with your phone and laptop catches fire while visiting a friend, at a BBQ party somewhere or in your car. If those items are listed in your property insurance, you can still get reimbursed. In this case, you will not just get coverage for the car itself. You’ll need comprehensive coverage under your auto insurance for that.
Does Renters Insurance Cover Smoke Damage Too?
Yes, it usually does. If smoke damage ruins your clothes, furniture, or electronics, even if there wasn’t direct fire, your renters insurance coverage will likely pay to replace those items. This includes smoke drifting in from a neighbor’s fire or a nearby wildfire. As long as the damage affects your personal property, and the fire wasn’t intentionally started by you, you’re covered.
Also, don’t forget, your loss of use coverage might step in as well. If smoke makes your apartment unlivable, your insurance policy could cover your temporary housing, meals, and other additional living expenses while you’re out. Just make sure to check your coverage limits, particularly if you’re living in a high-cost area.
So, What’s Usually Covered in a Fire at Your Rental?
If a fire occurs in your rental, renters insurance can cover your personal items that are damaged or destroyed, including everyday essentials and belongings stored off-site or in your car.
Here's a quick list of what’s typically covered under personal property coverage:
- Furniture (sofas, bed, dressers)
- Clothing and shoes
- Electronics (TVs, laptops, cameras, speakers)
- Kitchenware and small appliances
- Books, décor, and artwork
- Musical instruments
- Personal documents and valuables
- Luggage and items stored in closets or storage units
- Bikes, sports, gear, and hobbies
Please note that if these items are damaged by fire or smoke, your personal property coverage will reimburse them. However, any of these items, including gear, stuff stored in the storage units used for business purposes, may not be covered.
Also, if your rental apartment becomes uninhabitable due to fire damage and if you have loss of use or additional living expenses (ALE) coverage, you’ll receive compensation for the following things:
- Hotel stays
- Meals
- Extra transportation costs
- Laundry expenses
- Pet boarding
- Storage units fees
Types of Renters Insurance Coverage You Need for Fire Damage
Each coverage is different and designed to protect different situations and events. In case of house fires, you’ll need more than just the basic liability renters insurance policy.
Here are the key coverages you should have in place to avoid being underinsured when things go up in smoke/fire.
1. Personal Property Coverage
Personal property coverage is your primary shield when it comes to fire damage or smoke. It pays to repair or replace your damaged or destroyed personal belongings like furniture, clothes, electronics, and other essentials lost to fire damage or smoke.
Pro Tip: When choosing personal property coverage consider replacement cost coverage rather than actual cash value coverage. Replacement cost coverage generally pays what it costs to replace covered belongings with comparable new items, while actual cash value coverage factors in depreciation.
2. Loss of Use or Additional Living Expenses Coverage
If your place becomes uninhabitable, loss of use helps with temporary housing, meals, laundry, and more. These are additional living expenses that go beyond your normal rent. If you have this coverage, your hotel bills, short-term rentals, and extra commute costs will all be reimbursed.
3. Personal Liability Coverage
Although this coverage doesn’t directly protect your own property from fire, it can help if you accidentally cause a fire that damages someone else’s property or injures someone. It typically covers medical bills, property damage, or legal fees if the fire incident is your fault. Additionally, some landlords may require a minimum amount of liability insurance as part of your lease.
4. Riders or Endorsements (Optional)
If you own expensive or high-value items, such as jewelry, artwork, or certain electronics, your standard personal property coverage may not be enough to cover their full value. So, that’s why you should consider getting riders/endorsements for these high-value items. You can add a rider, endorsement or floater to extend your protection beyond their sub-limits, which can provide higher protection or full reimbursement for the stuff you care about most.
When Does Renters Insurance Not Cover Fire Damage?
Although renters insurance typically covers most accidental fires, it doesn’t cover all fire-related events. Here are the situations where your insurance company might deny your claim for fire damage:
- Intentional fires: If you or someone covered by your policy sets the fire on purpose, your claim will be denied.
- Pre-policy fires: Any fire that happened before your insurance policy started won’t be covered.
- Illegal activity: If the fire is tied to illegal acts, your claim may be denied.
- Negligent behavior: Repeated negligence or ignoring fire hazards could void coverage.
- Excluded perils: Some insurance policies may exclude wildfires or require a special add-on.
- Fire damaged the building: If the fire damages the structural part of the building, renters insurance will not cover you, as this responsibility falls on your landlord.
- Fire damage to your vehicle: If a fire damages your car, renters insurance won’t help. You’ll need a comprehensive auto insurance policy for that. However, any personal items inside the car that are burned are covered through renters insurance.
How Much Does Renters Insurance Pay You After a Fire?
It depends on your insurance policy, the value of your belongings, and the type of coverage you choose. Most renters insurance policies come with a personal property coverage limit, which is the maximum amount your insurance company will pay for everything damaged or destroyed by fire or smoke.
You’ll also need to pay a deductible first, which is typically $250 to $1,000. And you have to pay it before your claim is paid out, and if not, it probably would be deducted from your final payout.
If you have a replacement value coverage, the insurer will reimburse you for what it costs to buy a brand-new version of your items. If you have actual cash value (ACV), depreciation is factored in, which means you’ll get less.
Also, some categories, like electronics or jewelry, come with built-in special limitations, which is around $1,500, unless you’ve added extra coverage. Here’s a quick look:
Common Coverage Limit by Item
Item Type | Typical Coverage Sub-Limit |
Clothing | Full value (up to policy limit) |
Furniture | Full value (up to policy limit) |
Electronics (laptops, TVs) | $1500 to $2,500 unless you have added Scheduled Personal Property Coverage |
Jewelry and Watches | $1500 to $2,500 unless you have added Scheduled Personal Property Coverage |
Musical Instrument | $2,000 |
Art and Collectibles | $1,000 |
Cash | $200 |
Sports Equipment | $1,500 |
Kitchenware and Appliances | Full value (up to policy limit) |
Bikes | $1,000 to $2,000 unless you add a scheduled property endorsement |
How to File a Renters Insurance Claim for Fire Damage?
Claiming for fire damage through your renters insurance policy is fairly simple. Here are a few simple steps to file a claim for fire damage under your renters insurance coverage:
- Start by contacting your insurance company immediately after the fire. Report the incident, even if you’re still assessing the damage.
- Create an inventory of everything that was damaged or destroyed, along with estimated values. Photos, videos, and receipts help speed things up.
- Be honest and detailed when your insurer asks you to complete a proof of loss form.
- Your insurer may send an insurance adjuster who will assess the property damage. Make sure to fully cooperate and share any documents they request.
- And finally, track all communication and expenses, especially if you’re in temporary housing or paying for additional living expenses.
If you're having trouble with your renters insurance claim, make sure to contact your insurer promptly. If you're exploring an affordable renters insurance policy with the right coverage options for adequate protection, you can find and compare coverage options with L.A. Insurance.
Your Rights After a Fire: What State Laws Say
After a fire incident in your apartment, state laws generally require landlords to provide a safe, habitable living space. If your rental is unlivable, they must either make repairs quickly or let you end the lease without penalty.
In many states, you may also be entitled to a security deposit refund if you have to move out permanently. Some states offer extra protections like covering temporary housing costs or giving more time to pay rent after a disaster.
You’re also required to notify your landlord about the damage promptly. And while landlord responsibility covers the building, your renters insurance coverage handles your personal losses.
Things You Can Do If Your Apartment Is Unlivable Due to Fire Damage
A fire can leave you wondering where to sleep tonight and what to do next. The Tenant Resource Center suggests a few steps to take if you’re a victim of a house fire and your apartment is uninhabitable:
- Contact the Red Cross if you don’t have loss of use coverage or your insurance denies your claims. They often provide temporary shelter, food, and emergency supplies after home fires.
- Reach out to your landlord. Ask about temporary accommodation and the repair timeline. Whether your landlord must arrange or pay for temporary housing depends on local laws and your circumstances.
- Use your renters insurance. Your loss of use or additional living expenses coverage can pay for temporary housing, meals, or other essentials, Check for local shelters or community centers. They may offer short-term housing or support services.
The Bottom Line
Renters insurance does cover fire damage to your personal property inside your rental apartment, as long as you have personal property coverage. Also, your renters insurance may help pay for hotel stays, meals, and other necessities if your apartment becomes unlivable due to fire, through loss of use coverage.
At L.A. Insurance, we offer both of these coverages to tenants looking to protect themselves from a house fire. Whether you’re in Michigan, Colorado, Florida, Texas, Georgia, Arizona, or Nevada, L.A. Insurance is here for you when unforeseen events damage your rental space. If you need help, you can contact us today to get a free quote, and expert advice.
Frequently Asked Questions (FAQs)
How does renters insurance work with a fire?
Renters insurance typically covers personal belongings damaged by a covered fire. It may also pay for temporary housing and additional living expenses if your rental becomes uninhabitable. Your payout depends on your policy limits, deductible, and coverage terms.
Does renters insurance cover any injuries caused by the fire?
Yes, renters insurance may cover injuries caused by a fire if you're legally responsible. If someone is injured in your rental due to a covered fire, your personal liability coverage can help pay for their medical bills or legal costs. However, your own medical expenses are not covered under renters insurance; you’d need health insurance for that.
What happens if an accidental fire is caused by a tenant?
If you accidentally start a fire, your personal property coverage may help pay for your damaged belongings. If you're legally responsible for damage to the rental building or neighboring properties, your personal liability coverage may help cover the costs.
Does renters insurance cover temporary housing?
Yes, if your rental becomes unlivable, your loss of use coverage or additional living expenses coverage can help pay for hotels, short-term rentals, meals, and related costs.
How much does your insurance go up after a fire?
A renters insurance premium may increase by 27% to 29% after a first claim and 49% to 60% after a second claim. However, the actual increase depends on your insurer, claims history, and policy terms.
Does renters insurance cover everything after a fire?
No, renters insurance doesn't cover everything after a fire. It typically covers personal belongings damaged by a covered fire and may pay for temporary housing, subject to your policy's limits, deductible, and exclusions.
Editorial Disclaimer
The information provided on this blog is for general informational purposes only and does not constitute professional insurance, legal, or financial advice. Coverage and rates are subject to individual eligibility, underwriting guidelines, and state availability. For specific questions regarding your policy or to get an accurate quote, please contact a licensed L.A. Insurance agent directly. We're an independent agency and not a direct insurance carrier. For more information on how we operate and handle your data, please see our Terms and Conditions and Privacy Policy.
Tag :
Renter's insurance
best insurance
What is Universal Life Insurance?
If you’re exploring permanent life insurance options that provide a death benefit, cash value accumulation, and the flexibility to adjust premium payments, universal life insurance could be an option worth considering.
What is Whole Life Insurance?
If you're looking for a reliable life insurance policy that provides lifetime coverage and builds cash value over time, whole life insurance may be an option worth considering.
How Much is Car Insurance in Arizona?
If you're shopping for car insurance in Arizona, the first thing that comes to mind is the cost. Typically, car insurance premiums in Arizona range from $969 to $1,628 per year for full coverage.
Do You Need Insurance to Register a Car in Arizona?
Yes, you do need car insurance to register a car in Arizona, as it's legally mandatory. But here's the catch though, you don't need to submit proof of insurance to the MVD (Motor Vehicle Division) upfront when you initially register your car.
What is Permanent Life Insurance?
Wouldn’t it be helpful to have a life insurance policy that provides lifelong coverage and can also build cash value over time? That’s where permanent life insurance comes in.
What is Term Life Insurance?
Term life insurance is a type of life insurance policy that provides coverage for a specific period, generally 10, 15, 20, 30, or even 40 years.