Publish Date: 28-09-2026
Life Insurance
What Is Life Insurance?
If you’re thinking about getting a life insurance policy, it’s important to understand what it is and how it works. Simply put, life insurance is a type of financial protection that provides money to your chosen beneficiaries after your death. In return, you pay premiums to the insurance company to keep your coverage active.
Life insurance can help provide financial support for the people who depend on you, helping them manage expenses such as living costs, debts, childcare, education, or final expenses after your death. The type and amount of coverage you need can depend on your financial responsibilities, budget, and long-term goals.
How Does Life Insurance Work?
Life insurance works by providing a financial benefit to your beneficiaries in exchange for the premiums you pay to the insurance company. When you purchase a policy, you choose the amount of coverage and agree to pay premiums according to the policy terms.
If you die while the policy is active, your beneficiaries can generally file a claim with the insurer to receive the policy’s death benefit based on the policy’s terms and exclusions.
In simple terms, the process generally works like this:
- You purchase a policy: You apply for coverage and select a policy type and coverage amount.
- You pay premiums: You make regular payments to keep the policy in force.
- The policy provides coverage: Your beneficiaries are entitled to the death benefit if you die while the policy is active and the claim meets the policy requirements.
- Your beneficiaries file a claim: After your death, your beneficiaries submit the required documentation to the insurance company.
- The insurer pays the death benefit: If the claim is approved, the insurance company pays the benefit according to the policy terms.
Key Life Insurance Terms You Should Know
Before exploring the different types of life insurance, it’s helpful to understand some of the common terms used in life insurance policies. These terms explain who owns the policy, who is covered, what you pay for coverage, and what your beneficiaries may receive after your death.
Here are some key terms that you will come across while shopping for a life insurance policy.
- Policyholder: The person who owns the life insurance policy and is responsible for meeting its requirements, including paying premiums.
- Insured: The person whose life is covered by the policy. The death benefit is generally paid when the insured dies, subject to the policy terms.
- Beneficiary: The person or entity designated to receive the policy’s death benefit after the insured’s death. Premium: The amount you pay to the insurance company to maintain your life insurance coverage.
- Death Benefit: The amount the insurance company pays to the policy’s beneficiaries after the insured’s death, subject to the policy terms and exclusions.
- Coverage Amount: The amount of coverage provided by the policy, which generally corresponds to the death benefit payable to beneficiaries when a covered claim is approved.
- Policy Term: The period during which a life insurance policy provides coverage. This term is particularly relevant to term life insurance.
- Cash Value: A component of some permanent life insurance policies that can accumulate value over time.
- Rider: An optional provision that can add, modify, or expand certain benefits or features of a life insurance policy.
Who Needs Life Insurance?
If you have a spouse, children, or other people who depend on your income, life insurance is something you may want to consider. Let’s face a harsh truth; life is unpredictable, and an unexpected death can leave your loved ones facing financial responsibilities without your income or support.
Whether you’re 25 or approaching your 60s, unexpected death can occur at any age. If household members rely on your income, life insurance can provide a financial safety net to help them manage expenses and maintain financial stability after your passing.
Life insurance may be particularly relevant if you:
- Have a spouse or partner who depends on your income: The death benefit can help replace lost income and cover ongoing household expenses.
- Have children or other dependents: Coverage can help your beneficiaries manage childcare, education, and other expenses. Have outstanding debts: Life insurance can provide financial support for obligations such as a mortgage, personal loan, or other debts.
- Own a business: A life insurance policy may help address certain business-related financial obligations after your death.
If you want to plan for your final expenses and reduce the financial burden on your family, life insurance can also help provide funds for funeral and other end-of-life expenses.
If you’re considering an affordable life insurance policy, it’s helpful to compare quotes from multiple carriers through an insurance agency. With over 34 years of experience, our specialized life insurance agents at L.A. Insurance are here to provide expert recommendations and help you purchase a life insurance policy that truly meets your needs.
What Types of Life Insurance Are There?
There are two broad categories of life insurance, which include term life insurance and permanent life insurance. Term policies provide coverage for a specific period, while permanent policies are generally designed to provide lifelong coverage as long as the policy remains in force.
Final expense life insurance is another option designed to address specific end-of-life expenses. Here’s a brief look at the main types of life insurance and how they differ.
Term Life Insurance
Term life insurance provides you with coverage for a specific period, such as 10, 20, or 30 years. If you die while your policy is active, your beneficiaries can generally receive the death benefit according to the policy terms. However, your term life insurance policy expires if you outlive the policy period. In most cases, the premiums you have already paid are not refunded when the policy expires, unless your policy includes a return-of-premium feature.
Permanent Life Insurance
Permanent life insurance provides you with coverage for your entire lifetime, as long as you continue to meet the policy requirements and keep the policy active by regularly paying your premiums. Unlike term life insurance, permanent life insurance does not expire after a set number of years. Some permanent policies also include a cash value component that can grow over time.
There are three common types of permanent life insurance, each with different features and ways of building cash value as follows.
- Whole life insurance is a type of permanent life insurance that generally comes with fixed premiums and a guaranteed death benefit. Its cash value can grow over time at a guaranteed interest rate specified by the policy, allowing it to build consistently over the life of the policy.
- Universal life insurance is a type of permanent life insurance that provides lifelong coverage with more flexibility in premiums and death benefits. Its cash value earns interest based on the policy’s crediting method, which may be affected by market conditions.
- Variable life insurance is a type of permanent life insurance that allows you to invest the policy’s cash value in different investment options. The cash value can increase or decrease based on the performance of those investments.
Final Expense Life Insurance
Final expense life insurance is generally designed to help cover costs associated with a person's death, such as funeral and burial expenses. These policies typically offer a smaller death benefit than many other types of life insurance and can be an option for people primarily seeking coverage for end-of-life expenses.
What Does Life Insurance Cover?
Life insurance primarily provides financial protection after the policyholder’s death. If you die while your policy is active and the claim meets the policy requirements, your beneficiaries can generally receive a death benefit from the insurance company. They can use this money to help manage a variety of financial responsibilities.
Depending on your circumstances, the death benefit can help your beneficiaries cover:
- Everyday living expenses: Money for housing, food, utilities, and other household costs.
- Outstanding debts: Financial obligations such as a mortgage, personal loan, or other debts.
- Childcare and education expenses: Costs related to raising children and paying for their education.
- Funeral and final expenses: Expenses associated with your funeral, burial, or other end-of-life arrangements. Income replacement: Financial support that can help your family manage the loss of your income.
- Other financial needs: Your beneficiaries can generally use the death benefit for other expenses according to their needs and the policy terms.
What Does Life Insurance Not Cover?
While life insurance can provide a financial safety net for your loved ones, there are situations when your coverage may not apply. The specific exclusions can vary by policy and insurance company, so it’s important to review your policy terms carefully.
Some common situations that may be excluded or subject to specific policy provisions include.
- Suicide during the policy’s initial period: Many life insurance policies include a suicide exclusion during the first two years of coverage, although the exact period can vary by policy and state.
- Death resulting from fraud or misrepresentation: If you provide false or misleading information on your application, the insurer may deny a claim or take other action according to the policy terms.
- Death caused by excluded activities: Some policies may exclude certain high-risk activities or circumstances, depending on the policy provisions.
- Death during certain waiting periods: Some policies, particularly certain simplified-issue or guaranteed-issue policies, may have a waiting period before the full death benefit becomes available.
As exclusions and limitations vary, you should review the terms of your policy to understand when your beneficiaries may or may not receive the death benefit.
How Much Life Insurance Do You Need?
The amount of life insurance you need depends on the financial support your loved ones may require after your death. Your income, debts, household expenses, dependents, and future financial responsibilities can all play a role in determining an appropriate coverage amount.
For example, suppose you earn $60,000 a year, have a $200,000 mortgage, and have two children whose education you plan to support. In this situation, you may want enough life insurance to help replace your income, manage the mortgage, and contribute toward your children’s education and other household expenses.
Your existing savings and other financial resources are also important to consider when determining your coverage needs. Keep in mind that there is no single coverage amount that works for everyone, so your financial responsibilities, resources, and long-term goals can all affect how much life insurance you may need.
How Much Does Life Insurance Cost?
According to NerdWallet, the average cost of life insurance is around $26 per month, or $312 per year, for a 40-year-old with a $500,000 term life insurance policy for 20 years. By comparison, whole life insurance can cost around $418 to $480 per month, or approximately $5,023 to $5,753 per year.
However, your life insurance premium can vary based on factors such as your age, health, coverage amount, and policy type. So, the quotes you receive may therefore be different from these averages.
Which Type of Life Insurance Should You Choose?
The type of life insurance you choose depends on your financial responsibilities, coverage needs, budget, and long-term goals. There is no single policy type that works for everyone, so it’s important to consider what you want your coverage to accomplish. When choosing a life insurance policy, consider factors such as:
- How long you need coverage: If you need protection for a specific period, term life insurance may be an option to consider. If you want lifelong coverage, you may consider permanent life insurance.
- Your budget: Your premium can vary depending on the type and amount of coverage you choose. Consider a policy that provides the protection you need while fitting within your budget.
- Your financial responsibilities: Consider your income, debts, dependents, and other financial obligations when deciding what type of coverage may be appropriate.
- Your need for cash value: Some permanent life insurance policies include a cash value component, which may be an important consideration if you want this feature.
- Your long-term goals: Think about how you want your policy to support your loved ones and financial plans over time.
If you’re unsure which type of life insurance is appropriate for your situation, speaking with a life insurance agent can help you understand your options and choose coverage based on your individual needs.
Can You Get Life Insurance with a Pre-Existing Condition?
Having a pre-existing condition does not necessarily mean you cannot get life insurance. Many people with health conditions can still qualify for coverage, although their condition may affect the type of policy available, the coverage amount, or the premium they pay.
When you apply for life insurance, the insurance company may consider your overall health, the type and severity of your condition, your treatment history, age, lifestyle, and other factors. The underwriting process can also vary depending on the type of policy you choose. Some policies may have different eligibility requirements or may require less medical information than others.
If you have a pre-existing condition, it’s important to provide accurate information when applying for coverage. An experienced life insurance agent can help you understand your options and find coverage based on your individual circumstances.
How to Buy Life Insurance
Buying life insurance involves choosing the coverage you need, comparing your options, and completing an application with an insurance company. While the exact process can vary depending on the policy and insurer, the general steps include.
- Determine your coverage needs: Consider your income, debts, dependents, household expenses, and long-term financial goals to determine how much coverage you may need.
- Choose a type of life insurance: Decide whether term life insurance or permanent life insurance is more suitable for your coverage needs and financial situation.
- Compare life insurance options: Compare policies from different insurance companies based on coverage, premiums, policy features, and eligibility requirements.
- Complete an application: Provide information about your personal details, health, lifestyle, and financial situation as required by the insurer.
- Go through the underwriting process: Depending on the policy, the insurance company may review your application and health information to determine your eligibility and premium.
- Review and purchase your policy: Once you receive an offer, review the policy terms, coverage, premiums, and exclusions before accepting the policy and paying your premium.
How to Choose and Name Your Beneficiaries
Choosing your beneficiaries is an important part of getting a life insurance policy. Your beneficiary is the person or entity you name to receive the death benefit after your death. You can generally name one or more beneficiaries based on your wishes and financial circumstances.
When choosing and naming your beneficiaries, consider the following:
- Think about who depends on you financially: Your spouse, children, or other loved ones may be appropriate beneficiaries if they rely on your financial support.
- Consider multiple beneficiaries: You may name more than one beneficiary and specify how the death benefit should be divided among them, subject to the policy terms.
- Keep your beneficiary information updated: Major life events such as marriage, divorce, the birth of a child, or the death of a beneficiary may be reasons to review your designations.
- Understand primary and contingent beneficiaries: A primary beneficiary is first in line to receive the death benefit, while a contingent beneficiary may receive it if the primary beneficiary cannot receive the benefit.
Make sure your beneficiary designations are accurate and consistent with your financial plans. If you’re unsure who to name or how to structure your beneficiaries, a life insurance agent can help you understand your available options.
When’s the Best Time to Get a Life Insurance Policy?
There is no specific age that is the best time for everyone to get life insurance. However, getting coverage when you are younger and generally healthier may give you access to more affordable premiums and a wider range of policy options.
Your need for life insurance can also change as your financial responsibilities grow. Getting married, having children, taking on a mortgage or other debts, or becoming responsible for other family members can all be reasons to consider life insurance.
Even if you are older or have fewer financial dependents, life insurance may still be useful for covering final expenses, supporting loved ones, or addressing other financial needs. The right time to get a policy ultimately depends on your financial responsibilities, coverage needs, and long-term goals.
The Bottom Line: Is Life Insurance Worth It?
Yes, life insurance can be worth it if your loved ones depend on your income or may face financial difficulties after your death. The death benefit can help your beneficiaries manage expenses such as living costs, debts, education, and final expenses. However, the value of life insurance depends on your financial responsibilities, coverage needs, budget, and long-term goals.
If you’re considering life insurance and need help understanding your coverage options, you can contact us today for a free quote and expert advice. Our experienced life insurance agents can help you explore available policies and find coverage based on your needs.
Frequently Asked Questions (FAQs)
Can you have more than one life insurance policy?
Yes, you can have more than one life insurance policy. Having multiple policies may allow you to address different financial needs, such as income replacement, mortgage protection, or additional coverage for your family. However, insurers may consider your existing coverage when evaluating a new application.
What happens if you stop paying life insurance premiums?
If you stop paying your premiums, your policy may eventually lapse and your coverage may end. Some policies may provide a grace period or other options to keep the policy in force, depending on the policy terms. If you are having difficulty making payments, contact your insurer before allowing the policy to lapse.
Does life insurance expire?
It depends on the type of policy. Term life insurance provides coverage for a specific period and generally expires when that period ends. Permanent life insurance is designed to provide lifelong coverage as long as the policy remains in force.
Can you get life insurance after a policy lapses?
You may be able to reinstate a lapsed life insurance policy or purchase a new policy, depending on your circumstances and the insurer's requirements. Reinstatement may involve paying overdue premiums and providing updated health information.
How long does it take beneficiaries to receive life insurance benefits?
The time it takes to receive a life insurance death benefit can vary depending on the insurer, the claim, and whether the required documentation has been provided. Beneficiaries generally need to submit a claim and supporting documents to the insurance company before the benefit can be paid.
Can you get life insurance without a medical exam?
Yes, some life insurance policies allow you to apply without a traditional medical exam. The insurer may instead use information from your application and other available records to determine your eligibility and premium. These policies may have different coverage limits and eligibility requirements.
Editorial Disclaimer
The resources on this blog are researched and created by experienced insurance writers, then fact-checked and verified for accuracy to provide clear, general informational guidance. This content does not constitute professional insurance, legal, or financial advice. Coverage options and premium rates are subject to individual eligibility, underwriting guidelines, and state availability. For specific questions regarding your policy or to get an accurate quote, please contact a licensed L.A. Insurance agent directly. We're an independent agency and not a direct insurance carrier. For more information on how we operate and handle your data, please see our Terms and Conditions and Privacy Policy.
Tag :
Life Insurance
best insurance
LA Insurance
What Is Life Insurance?
If you’re thinking about getting a life insurance policy, it’s important to understand what it is and how it works. Simply put, life insurance is a type of financial protection that provides money to your chosen beneficiaries after your death.

Does Car Insurance Cover Rust Damage?
Rust can damage many parts of your car and may become more severe over time if left untreated.
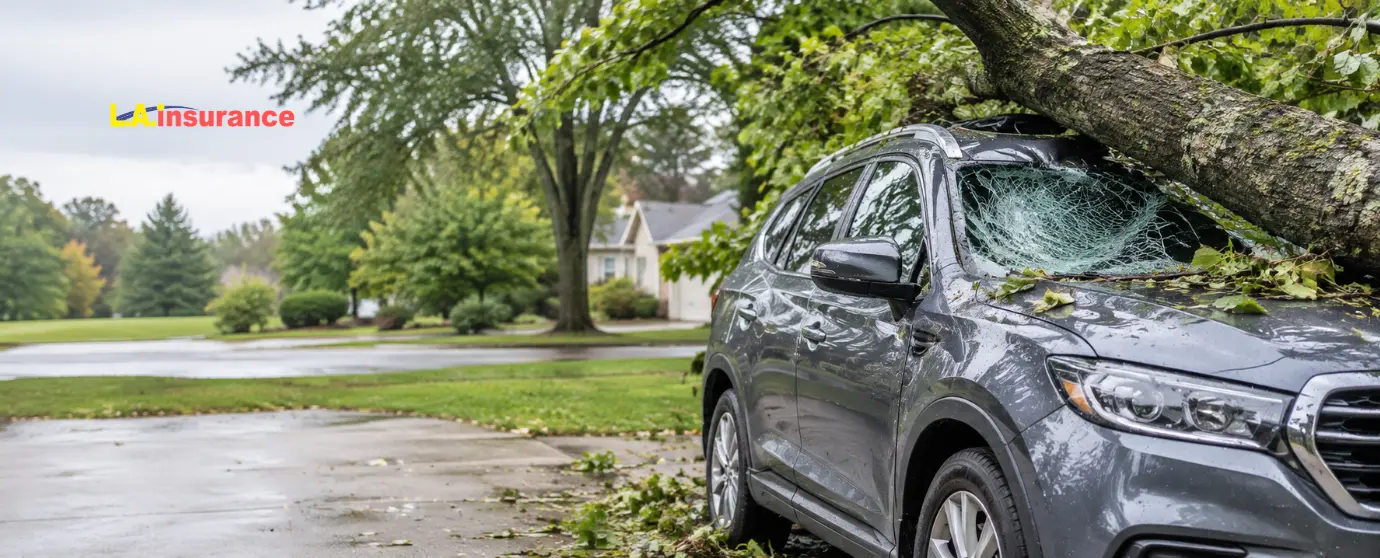
Does Insurance Cover a Tree Falling on Your Car?
Whether your car is parked out in the open under or near a tree, or you’re driving when a tree suddenly falls on your car, either way, it can leave your car severely damaged or even wrecked.
Does Car Insurance Cover Snow Damage?
Your car is more susceptible to damage in winter when it snows. As long as it’s out in the open, it can get damaged by snow at any moment.
Does Auto Insurance Cover Pets in the Car?
Whether you regularly drive with your pets in the car or only take them along occasionally, it’s worth knowing whether your auto insurance covers them.
Do You Need Car Insurance to Cover Road Trips?
If you’re wondering whether your standard auto insurance covers road trips, the good news is that it typically does.